Showing posts with label 17. Making decisions with uncertainty. Show all posts

Monday, October 12, 2026

Columbus Day and the Risks of Exploration

Although Columbus is criticized for the exploitation, enslavement, and suffering associated with European colonization, his voyages offer an instructive example of the risks of investing in exploration. In 1492, Spain's monarchs financed an expedition to find a commercially valuable route to Asia, uncertain whether Columbus would succeed—or even return. But there was another risk: would he be able to claim the rewards of a successful voyage? The Capitulations of Santa Fe promised Columbus hereditary privileges, including the offices of Viceroy and Governor of the territories he discovered. Yet the Crown subsequently removed him from office, and after decades of litigation, his heirs lost their claims to those hereditary governorships. The Treaty of Tordesillas of 1494 sought to reduce another source of uncertainty by dividing overseas claims between Spain and Portugal, although other nations and Indigenous peoples were not parties to the agreement. 

Five centuries later, companies exploring the ocean floor face similar uncertainties. ABC News reports that some companies hope to recover valuable nickel, cobalt, and other minerals from the deep ocean. But collecting minerals thousands of meters underwater is technically difficult and commercial profitability remains unproven. In August, NOAA announced that it had advanced its review of an application by The Metals Company to explore and commercially recover minerals from the Pacific seabed. Even if the technology works, property rights remain uncertain. The United States has its own permitting process, but the International Seabed Authority maintains that mining in international waters requires authorization under its international framework.

Both ventures illustrate two distinct risks of exploration: the technology may fail, and even if it succeeds, (perhaps because it succeeds) the claim to the rewards may fail. The expected return on investment depends on both probabilities. Property rights are valuable only to the extent that they can be enforced.

Sunday, October 11, 2026

Immigration Policy and the Two Types of Errors

When screening applicants, there are two ways to make a mistake. A Type I error occurs when someone who should be rejected is admitted. A Type II error occurs when someone who should be admitted is rejected. Immigration policy faces this tradeoff. Tightening screening and admission requirements may reduce the first type of error, but it can also increase the second. The challenge is to balance the costs of admitting someone who should not enter against the costs of excluding someone who could benefit the country.

The stated Trump administration immigration policy has been to reduce Type I errors, reduce illegal immigration. Collateral damage is an increase in Type II errors, fewer legal immigrants. The Cato Institute reports that legal immigration fell substantially more than illegal immigration. Comparing monthly entry figures through February 2026 with those before Trump took office, Cato estimates that legal entries fell by approximately 145,000, while illegal entries fell by about 53,000. The restrictions affect people seeking admission through established legal channels, including employment, family reunification, and education. A full error cost analysis would require an estimate of the cost to society of typical illegal entrants and the lost benefit of typical legal entrants. It is open to debate, but evidence suggests that immigration is a net positive and that illegal immigrants to the US are not a cost.

One frequently hears that potential immigrants should simply follow the legal process. This offers little guidance if that too is unavailable.

Tuesday, September 29, 2026

Does Surgery Work?

 The Economist: Many surgical interventions are little better than placebo


The results are upending the field. Removing an inflamed appendix, an operation that around 5-10% of people have had at some point in their life, has turned out to be no better for most patients than a course of antibiotics. Trials comparing different surgical techniques have also revealed that cheaper and less complex operations can be more effective. Most striking, the data show that some widely used surgical procedures, such as spinal fusions and rotator-cuff repairs, have effects indistinguishable from placebo or non-surgical care such as physiotherapy.
Worse, some types of surgery may do more harm than good. A trial in Britain found that prostate-cancer surgery had no effect on patient mortality 15 years on, but worsened sexual and urological problems. A Finnish trial of a common knee procedure, meanwhile, concluded that patients who had real surgery had more problems in the affected knee ten years on than those who had had sham surgery (anaesthesia followed by a superficial incision). David Ring, an orthopaedic surgeon at the University of Texas at Austin, reckons that most operations in his field may be unnecessary. Surgery itself, it would seem, could use a major intervention.

WWA (World Weather Attribution) cashing in using flawed methodology

From The Free Press: 

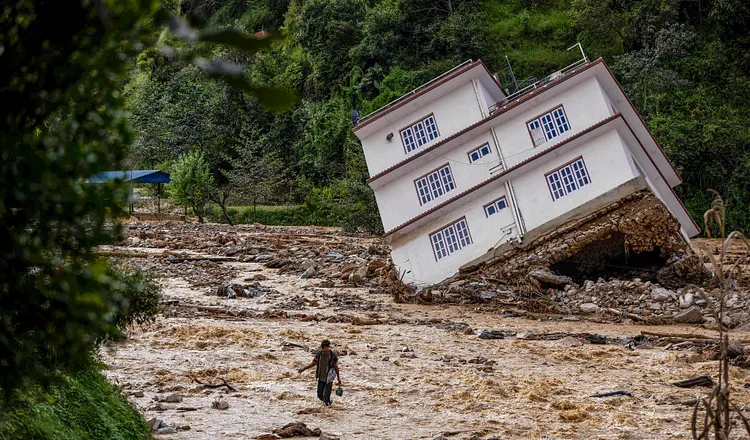
On August 26, a wall of rock and ice broke away from Langtang Lirung in the Himalayas, resulting in a massive flood and mudflow that killed thousands of people along the border of Nepal and Tibet. Less than a month later, on September 17, an influential organization called World Weather Attribution (WWA), housed at Imperial College London, published a report on the catastrophe along with a press release touting its alarming findings.
What the WWA does: 
 
Motivated Reasoning:
WWA has not been shy about the fact that it produces its studies to influence the public and to promote climate advocacy. Authors of one of the WWA’s foundational papers openly acknowledged that a primary reason for creating their methods is political: by “increasing the ‘immediacy’ of climate change, thereby increasing support for mitigation.” 
Detection by Correlation and Attribution by Assumption
...WWA treats “climate change,” measured as a smoothed record of global temperature, as the only possible cause of any localized trend in rainfall, heat, flooding, or other types of extreme weather.
People are fooled
The WWA’s advocacy campaign has worked brilliantly, of course; 50 percent of Americans now believe policies addressing climate change would reduce the number or severity of the extreme weather events that they individually, or their communities, will experience. 
Who funds these idiots?
WWA’s funders are philanthropists: the Grantham Foundation, the European Climate Foundation, and the Bezos Earth Fund, three of the largest backers of climate advocacy in the world.
What the methodology should do (IPCC, Intergovernmental Panel on Climate Change):
The first step is detection: whether the long-term statistics associated with a particular type of extreme weather change—a century of hurricane landfalls, say, or peak river flows—can’t be explained by the normal fluctuations in weather over years and decades, called internal climate variability.  [COMMENT:  this is extraordinarily difficult given the long run cycles in climate data]
The second step is attribution: The IPCC starts with a detected change and assesses the possible causes underlying that change—greenhouse gases, aerosols, volcanoes, land use, modes of climate variability, etc.—using sophisticated computer models of the earth’s climate system.  [COMMENT:  ruling out alternative explanations from non-experimental data is also extraordinarily difficult].
IPCC Findings: 
The scientific reality—long understood in mainstream climate science—is that any emissions policy a government adopts today will not noticeably reduce the frequency and intensity of extreme weather, through the lifetimes of children or their children’s children.
If lack of knowledge were the problem, I would send WWA a copy of Chapter 17:  Making Decisions with Uncertainty

Tuesday, September 22, 2026

When Winning Is a Budget Risk: Hedging Coaching Bonuses

Prediction-market trades have turned up whose payouts nearly match college football coaches' playoff bonuses. Five line up almost exactly with Lane Kiffin's bonuses at LSU. The schools didn't place them, but third parties acting for them plausibly did.

Why would a school bet on its own success? Coaching contracts promise big bonuses for making the playoffs, advancing and winning a title. A deep playoff run can leave the athletic department owing millions it didn't budget for. A contract that pays off when the team wins covers that bill when it comes due. Like a farmer locking in a crop price, the school gives up some upside in exchange for a predictable budget.

Why go through a third party? NCAA rules forbid athletic staff from betting on games, and prediction markets count. So a school can instead pay an insurer a premium, and the insurer buys the contracts itself.

Takeaways:

  • A performance bonus is a bill that only comes due when things go well.
  • If people are betting on whether that success happens, you can buy a bet that pays for the bill.
  • As budgets tighten and these betting markets grow, expect more of this.

Source: Josh Hendrickson, Insuring Against Success?, Economic Forces

Wednesday, June 24, 2026

Extracting Information from Supply Disruptions

On Sept. 16, 2025, a fire at Novelis's aluminum rolling mill in Oswego, New York disrupted roughly 40 percent of the automotive aluminum sheet used in North America. The importance of this supply disruption can be determined using standard stock market event study analyses. Ford was one of the firms most exposed to the disruption because it relied heavily on automotive aluminum sheet. As analysts began estimating the impact on vehicle production and profitability, Ford's stock price fell sharply. Similarly, investors also penalized Hindalco, Novelis's parent company. The interesting question is what happened to competitors. If one supplier exits temporarily, shouldn't rivals benefit?

Firm

Relationship to Event

Approximate Stock Market Reaction

Ford

Customer of automotive aluminum sheet

-7% abnormal return

Hindalco (owner of Novelis)

Directly affected supplier

-6% abnormal return

Kaiser Aluminum

Potential substitute supplier

+3% to +5% short-term gain

Constellium

Potential substitute supplier

Little measurable effect

Investors appeared to believe that Ford would suffer large costs from the disruption, but they did not assign equally large gains to Novelis's competitors. While aluminum itself is a commodity, automotive aluminum sheet is not. Suppliers must invest in specialized equipment, satisfy demanding quality standards, and undergo lengthy qualification processes with automakers. Even if competitors wanted to absorb Novelis's lost volume, they may not have had sufficient spare capacity or approved production lines to do so quickly. Ford's stock market loss was several times larger than analysts' estimates of immediate production costs because investors recognized that replacing a critical supplier is expensive and time-consuming. There are no doubt benefits to Ford and Novelis from contract exclusivity. This episode highlights the costs.

Saturday, May 16, 2026

Fabulous post on central planning from MarginalRevolution

If our textbook gets to an eight edition, this will make it into Chapter 1.

MarginalRevolution on Central Planning:

The dilemma is this. There is a problem of information. Supercomputers will in fact help process information better. But if the information coming in is junk, and if that junk is built into the system because of the incentives that operators have in workplaces to lie, you will not have a planning system that can be put on its feet through the advent of computers or artificial intelligence or anything like that. I don’t see any reason to think that that strategic misalignment of incentives is simply there because of Russian backwardness or poverty.

..the burden of proof is on us, on the Left, if we want to continue with this slogan of replacing the market with the plan. The burden of proof is on us to show that it can work. You might say that along with this ought to come a kind of humility about facts and about the world. ... it would be criminally negligent to ignore the experience of decades upon decades of planning and say to yourself, “Well, that wasn’t what my vision of socialism is, so I’m going to ignore it.” Because if you do that, I can guarantee 100 percent you will end up repeating many of the mistakes and falling into the same dilemmas that the planners did. 


Monday, May 11, 2026

FDA screens out studies with selection bias

The Free Press:
  • ..one of the studies looked at a group of people for six weeks—three weeks after they were vaccinated, and then another three weeks after that. If they were healthy after the second three-week period, the researchers concluded that it meant the vaccine was safe. In addition to the absurdly short length of time—six weeks to conclude the vaccine is safe?—it has an obvious and inherent bias toward healthy people, who are the most likely to get vaccinated. 
  •  Another study used an approach called “test negative”: It looked at people who came to the hospital with flu-like symptoms, some of whom had Covid and some of whom didn’t. If the group who were vaccinated had fewer people with Covid, it was supposed to mean that the vaccine worked. But in reality, it could simply mean that people who are vaccinated are more likely to show up at the hospital.

Wednesday, April 29, 2026

Algorithmic Pricing Paper by some middling economist

Froeb, Luke M. and Tschantz, Steven T. and Sokol, D. Daniel, Algorithmic Pricing When Capacity Turns Over: Competition, Collusion, and Information Sharing (April 29, 2026). Available at SSRN: https://ssrn.com/abstract=6675958 

BOTTOM LINE: 
First, sharing occupancy information intensifies competition, as firms compete in each realized state rather than on average. Second, as occupancy rises, it becomes more difficult to absorb diverted rival demand, so firms become worse substitutes for each other, shrinking the gains to collusion. Third, scale pools demand risk, raising occupancy and lowering prices. 

 Together, these findings identify a structural channel through which algorithmic pricing in capacity-constrained markets generates efficiency gains rather than collusive overcharges. ... The results yield practical guidance on which pricing algorithm to adopt and what information to feed it.

Monday, April 27, 2026

GLP-1 and Wedding Dress Uncertainty


Many a bride has chosen a dress a bit too small in anticipation of losing a few pounds before the big day. Sometimes they miss their goals. Bridal studios have long anticipated and planned for this. But with GLP-1 weigh loss medications, the dieting goals have become more ambitious. Even when the weight goals are met, the changes in body shape may not be what was anticipated. An ill-fitting dress, and unhappy bride, is even more likely. There is more uncertainty in the bridal dress business.

As the WSJ reports,bridal studios are trying to accommodate. They are handling more rush orders due to selections made later after gauging weight loss progress, holding more inventories of near-miss sizes and late dress change options, and trying to fit in more last minute alteration requests. All of these adjustments to accommodate the additional uncertainty imply additional costs. As if wedding planning wasn't anxiety inducing enough.


Friday, February 27, 2026

The Rise of Prediction Markets

The idea of prediction markets may have begun as a small research tool in Iowa in the 1980s with trading volumes measured in the thousands of dollars. After a few decades, monthly dollar volume for private prediction markets had reached millions of dollars. Recently, prediction markets have hit the big time. The WSJ reports that Polymarket and Kalshi now do about $3-4 billion of volume in a month. To be sure, this is still three orders of magnitude smaller than the volume of the NYSE or NASDAQ of $2-3 trillion. But this impressive growth indicates broad acceptance. 

The idea is simple. If a contract will pay $1 if an event occurs and I think the event will occur with probability P, my expected value of owning the contract is $1 x P or $P. If it is currently trading for less (more) than $P, I can expect to make money buying (selling) the contract. With enough  potential traders, the price being quoted is "the market's" best estimate of the probability of the event. Traders' profit motives drive the price to the "the market's" expectation.

Non-traders, perhaps ignorant of how new information will affect the probability, need only look at how much the price has changed to infer what more knowledgeable individuals think of the information. Prediction markets harness "the wisdom of the crowd." The growth of these markets is an indicator of how valuable this information can be.

Wednesday, February 11, 2026

What drives the male-female wage gap?

Economist:  Motherhood 
  • Researchers took women undergoing in vitro fertilisation (IVF)—who clearly wanted children—and examined the difference in long-term wages between those who fell pregnant and those who did not. At first the mothers earned much less, but this gap shrank over time. 
  • Now this approach of exploiting natural variation in fertility has been used in a new study, by Camille Landais of the London School of Economics and others. 
    • It looks at women with Mayer-Rokitansky-Küster-Hauser (MRKH) syndrome, a rare condition in which a girl is born without a uterus but otherwise develops normally. These women know early in life that they will not bear children, ...
    • Such early knowledge seems to make a big difference. ... Their wage trajectory is almost identical to that of their male peers. 
    • In other words, remove both motherhood and any decisions women might make while anticipating it, and the wage gap seems to vanish. 

Differences-in-Differences: Handwashing and Waterborne Transmission of Cholera

 From: Carlos Chavez, On Causality

Difference-in-differences has undergone a methodological renaissance. The method’s intellectual roots reach back further than most economists realize - to the 1840s and 1850s.
  • In 1847, Ignaz Semmelweis used comparative clinic analysis to show that handwashing prevented childbed fever, comparing mortality between Vienna’s physician-staffed ward (where medical students performed autopsies) and its midwife-staffed ward, then tracking outcomes after implementing chlorine disinfection.
  •  John Snow’s 1854 investigation of cholera in London is credited as the first recorded application of difference-in-differences proper. Snow compared mortality rates across households served by two water companies: the Lambeth Company, which had moved its intake upstream of the city’s sewage outflow in 1852, and the Southwark & Vauxhall Company, which continued drawing contaminated water. By comparing changes in cholera deaths before and after Lambeth’s relocation - while Southwark & Vauxhall served as the control - Snow produced a cleaner diff-in-diff design, with parallel pre-treatment trends giving way to dramatic divergence. His “Grand Experiment” found 315 deaths per 10,000 households among Southwark & Vauxhall customers versus only 37 per 10,000 among Lambeth customers, providing powerful evidence for the waterborne transmission of cholera decades before germ theory was established.

Friday, January 30, 2026

Border Security Type I and Type II Errors

One way of looking at the a policy of increased ICE enforcement of US border security is as a debate over decision error costs. The expressed goal is to remove the worst of the worst criminals. Few would disagree with this goal. However, in this dragnet, immigrants without criminal backgrounds have also been detained. The administration may see this as representing a small cost to pay, while the protesters see this as an unacceptable consequence.

The graphic below from the Financial Times indicates how many more criminal and non-criminal detainees the policy change has resulted in. Your position in this debate likely comes down to whether you think the benefit of detaining ~6,000 more criminals outweighs the cost of detaining ~25,000 more with no criminal background. Reasonable people can disagree over what would be acceptable, but few have stated what value they consider to be acceptable.

(I understand there is also debate over what are acceptable detention tactics.)

Sunday, December 14, 2025

Arbitrage Fueled by Data Analytics

Reuters reports that Williams-Sonoma recently sued "dupe" producer, Quince, for an unfair comparison. Dupe producers include online retailers who make copies of popular high-end items that often include high margins. 

"By brand-washing its ads, Quince creates the false impression that consumers will receive comparable quality and design, when in reality they may be purchasing unrelated items of often inferior quality," Williams-Sonoma said.

Quince seems to have struck a nerve. It mostly sells apparel targeted to women aged 25 to 55 and women’s business accounts for about 80% of its sales. Quince uses data analytics to determine what is hot at other retailers and then scours the customer reviews for areas of improvements. “Things like, where are the pockets, what zipper, quality of the hardware,” Of course, it is implementing AI to speed up production of its dupes. Fashion is especially vulnerable to this sort of arbitrage because the IP protections generally do not apply.

Monday, August 4, 2025

Data Driven Decision-making ... or visa versa

The furor over the president's recent firing the BLS director over unfavorable revisions to the jobs numbers highlights an issue with all data driven decision making. Firms are increasingly turning to data to inform strategic decision making. However, often managers consider the new requirement of empirical support for a decision to be a nuisance. Instead, they seek to find analyses that support their prior beliefs. A useful check against this "cherry-picking" of the data is to vest the data analysis team with some autonomy from the decision maker.

Reproduced below is a graph from Vincent Geleso (who credits Gary Wagner) that tracks BLS jobs revisions over the last quarter-century. It appears that data revisions are common, are both positive and negative, are not biased up or down, are often large, and most importantly are non-partisan. This suggests that the recent revisions were not out of the ordinary. Non-independence of future BLS data reporting from partisan priorities will likely render their future reports to be more suspect. 

Hat tip: Marginal Revolution

Wednesday, June 18, 2025

PolyMarket.com predicts outcomes of Israel-Iran conflict

Probability      Event

66%                US Military action against Iran by July?

59%                Khameni out as Supreme Leader of Iran by 2025?

59%                Fordow nuclear facility destroyed before July?

--------UPDATED Jun 18, 2025 (link)---------

Friday, November 15, 2024

How the Trump Whale made money betting on prediction markets

WSJ:
Polymarket’s remarkable liquidity explains Théo, the Polymarket whale [who made $85 million]. Théo behaved as one would expect of a smart trader: Once he had conviction, he sized the trade aggressively. He built his positions discreetly, with a variety of wallets and with small-sized buys, to avoid causing a run-up in price. This is exactly the opposite of what one would expect if, as much of the media and BlueAnon claimed, he was throwing away dozens of millions to influence the election.
More important, Théo did his own research. Rather than rely on polls, he theorized that there was a strong “shy Trumper” effect. That is, he believed that Trump supporters were both less likely to talk to pollsters and less likely to tell pollsters that they would vote for the former president. As he told The Wall Street Journal in an email, he commissioned his own surveys in which respondents were asked who they thought their neighbors would vote for. The results “were mind blowing to the favor of Trump!”
Not only did Théo bet that Trump would win the Electoral College. He also bet that Trump would win the popular vote—an outcome that was the minority position even on Polymarket—and that Trump would sweep six of seven swing states, including the “blue wall” of Michigan, Pennsylvania and Wisconsin.

Tuesday, October 29, 2024

Correlation is not causation: birth weight determines mortality, not the animus of white physicians

Economist: 

CORRELATION: “when Black newborns are cared for by Black physicians, the mortality penalty they suffer, as compared with White infants, is halved.” 

MISTAKENLY INFERRING CAUSALITY FROM CORRELATION:
This striking finding quickly captured national and international headlines, and generated nearly 700 Google Scholar citations. The study was widely interpreted—incorrectly, say the authors—as evidence that newborns should be matched to doctors of the same race, or that white doctors harboured racial animus against black babies. It even made it into the Supreme Court’s records as an argument in favour of affirmative action, with Justice Ketanji Brown Jackson (mis)citing the findings. A supporting brief by the Association of American Medical Colleges and 45 other organisations mentioned the study as evidence that “For high-risk black newborns, having a black physician is tantamount to a miracle drug.”

CAUSALITY:  birth weight determines mortality, not the animus of white physicians

...a disproportionately high share of underweight black babies were treated by white doctors, while a disproportionately high share of healthy-weight black babies were treated by black doctors.
IRONY:
That a flawed social-science finding which fitted neatly within the zeitgeist was widely accepted is understandable. Less understandable is that few people now seem eager to correct the record. The new study has had just one Google Scholar citation and no mainstream news coverage.