Friday, October 9, 2026

War Provides Arbitrage Opportunities


Arbitrageurs profit by buying where prices are low and selling where prices are high. But what happens when transporting the product is dangerous? According to The Wall Street Journal, oil producers in the Persian Gulf are paying $30–$40 million for tankers to make dangerous trips through the Strait of Hormuz. The tankers carry oil out of the Gulf and transfer it to other vessels for delivery to customers. Some sailors are being offered bonuses of up to $25,000 per trip. While buyers are reluctant to send their own tankers into the Gulf, producers are willing to pay extraordinary sums to get their oil to market.

The disruption has also affected oil shipments far from the Persian Gulf. Reuters reports that shipping two million barrels of U.S. crude from the Gulf of Mexico to China now costs approximately $80 million, or $40 per barrel, compared with just $8.60 per barrel before the war. The elaborate shuttle operations in the Persian Gulf have tied up tankers, reducing their availability elsewhere. Freight rates have risen so much that traders say the arbitrage opportunity for shipping U.S. oil to Asia has disappeared. Asian refiners are consequently considering alternative suppliers in the Middle East and Latin America.

The arbitrage cost is comparable in magnitude to the increase in Brent crude prices since the war began. The ability to exploit this form of arbitrage essentially put a cap on how much the price rose between between the well and the refinery.

Diminishing Marginal Utility of Yodeling

One reason demand curves slope downward is that people tend to tire of repetition. This is what Mark Twain discovered hiking in Swiss Alps

The jodling (pronounced yodling,—emphasis on the o,) continued, and was very pleasant and inspiring to hear. Now the jodler appeared,—a shepherd boy of sixteen,—and in our gladness and gratitude we gave him a franc to jodel some more. So he jodled, and we listened. We moved on, presently, and he generously jodled us out of sight. After about fifteen minutes we came across another shepherd boy who was jodling, and gave him half a franc to keep it up. After that, we found another jodler every ten minutes; we gave the first eight cents, the second one six cents, the third one four, the fifth one a penny, contribution nothing to Nos. 5, 6, and 7, and during the remainder of the day hired the rest of the jodlers, at a franc apiece, not to jodel any more. There is somewhat too much of this jodling in the Alps.

[Mark Twain, A Tramp Abroad: Following the Equator, Other Travels, edited by Roy Blount Jr. (New York: Library of America, 2010), p. 187]

Saturday, October 3, 2026

Why Buyers Hate Auctions

When Salad and Go filed for bankruptcy in August, it already had a buyer. Dutch Bros had agreed to pay $105 million for as many as 65 of the failed chain’s drive-through locations. But rival 7 Brew was also interested in the properties and objected to the private deal. Should the bankruptcy court switch to negotiations with 7 Brew? Instead it approved an auction between Dutch Bros and 7 Brew. On August 31, 2026, Dutch Bros announced that it would not raise its offer, and 7 Brew emerged as the winner. After adjustments to the number of leases included in the transaction, the court approved a sale of 63 locations to 7 Brew for about $123.5 million—roughly $18.5 million more than the original Dutch Bros deal.

Sellers should prefer auctions to simply negotiating with a willing buyer. In bilateral bargaining, Dutch Bros has every reason to convince Salad and Go that $105 million is about as high as it will go. But the arrival of another bidder changes the negotiation. Instead of the seller having to determine how much each buyer is willing to pay, the buyers reveal information about their valuations by competing against one another. Indeed, Dutch Bros ultimately chose not to increase its offer, effectively revealing where further bidding stopped making sense for it. Buyers naturally prefer to negotiate without a competitor standing beside them. Sellers prefer exactly the opposite.

Tuesday, September 29, 2026

Does Surgery Work?

 The Economist: Many surgical interventions are little better than placebo


The results are upending the field. Removing an inflamed appendix, an operation that around 5-10% of people have had at some point in their life, has turned out to be no better for most patients than a course of antibiotics. Trials comparing different surgical techniques have also revealed that cheaper and less complex operations can be more effective. Most striking, the data show that some widely used surgical procedures, such as spinal fusions and rotator-cuff repairs, have effects indistinguishable from placebo or non-surgical care such as physiotherapy.
Worse, some types of surgery may do more harm than good. A trial in Britain found that prostate-cancer surgery had no effect on patient mortality 15 years on, but worsened sexual and urological problems. A Finnish trial of a common knee procedure, meanwhile, concluded that patients who had real surgery had more problems in the affected knee ten years on than those who had had sham surgery (anaesthesia followed by a superficial incision). David Ring, an orthopaedic surgeon at the University of Texas at Austin, reckons that most operations in his field may be unnecessary. Surgery itself, it would seem, could use a major intervention.

WWA (World Weather Attribution) cashing in using flawed methodology

From The Free Press: 

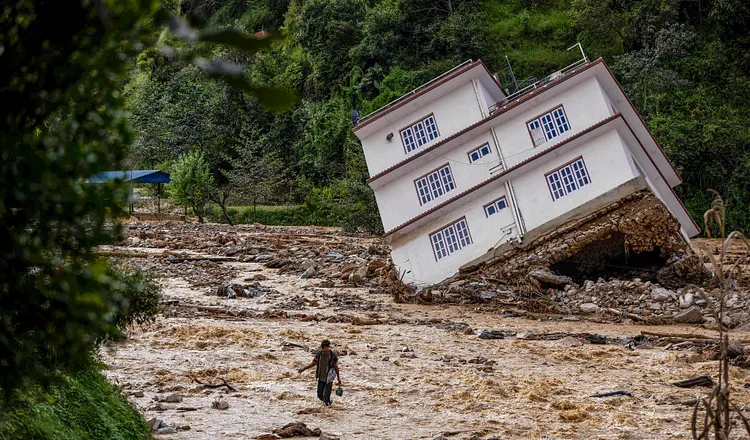
On August 26, a wall of rock and ice broke away from Langtang Lirung in the Himalayas, resulting in a massive flood and mudflow that killed thousands of people along the border of Nepal and Tibet. Less than a month later, on September 17, an influential organization called World Weather Attribution (WWA), housed at Imperial College London, published a report on the catastrophe along with a press release touting its alarming findings.
What the WWA does: 
 
Motivated Reasoning:
WWA has not been shy about the fact that it produces its studies to influence the public and to promote climate advocacy. Authors of one of the WWA’s foundational papers openly acknowledged that a primary reason for creating their methods is political: by “increasing the ‘immediacy’ of climate change, thereby increasing support for mitigation.” 
Detection by Correlation and Attribution by Assumption
...WWA treats “climate change,” measured as a smoothed record of global temperature, as the only possible cause of any localized trend in rainfall, heat, flooding, or other types of extreme weather.
People are fooled
The WWA’s advocacy campaign has worked brilliantly, of course; 50 percent of Americans now believe policies addressing climate change would reduce the number or severity of the extreme weather events that they individually, or their communities, will experience. 
Who funds these idiots?
WWA’s funders are philanthropists: the Grantham Foundation, the European Climate Foundation, and the Bezos Earth Fund, three of the largest backers of climate advocacy in the world.
What the methodology should do (IPCC, Intergovernmental Panel on Climate Change):
The first step is detection: whether the long-term statistics associated with a particular type of extreme weather change—a century of hurricane landfalls, say, or peak river flows—can’t be explained by the normal fluctuations in weather over years and decades, called internal climate variability.  [COMMENT:  this is extraordinarily difficult given the long run cycles in climate data]
The second step is attribution: The IPCC starts with a detected change and assesses the possible causes underlying that change—greenhouse gases, aerosols, volcanoes, land use, modes of climate variability, etc.—using sophisticated computer models of the earth’s climate system.  [COMMENT:  ruling out alternative explanations from non-experimental data is also extraordinarily difficult].
IPCC Findings: 
The scientific reality—long understood in mainstream climate science—is that any emissions policy a government adopts today will not noticeably reduce the frequency and intensity of extreme weather, through the lifetimes of children or their children’s children.
If lack of knowledge were the problem, I would send WWA a copy of Chapter 17:  Making Decisions with Uncertainty

How to Sell Meta Glasses (and Car Stereos)


Best Buy is moving in two seemingly opposite directions with in-store product demonstrations. In June, it announced that Meta Labs will open in more than 50 Best Buy stores. The 900-square-foot spaces let customers try Meta’s AI glasses and VR headsets, use interactive displays and smart mirrors, receive personalized fittings, and talk with dedicated Meta specialists. Yet just weeks later, Best Buy reportedly began removing many of its traditional car-audio demonstration displays, some of which had missing products or simply did not work. Demonstrations aren’t disappearing altogether: car-audio manufacturers including Sony, Pioneer, Kenwood, JVC, and Kicker have been paying for their own branded displays, now found in about 300 Best Buy stores.

The contrast highlights retailer actions boosting manufacturer demand. Helping a customer experience a pair of smart glasses may increase demand for Meta’s product, but Best Buy bears much of the cost of providing the service. Worse, customers can learn about a product at Best Buy and then buy it elsewhere—the classic retail-services free-rider problem. Meta’s solution is to become more deeply involved in the retail experience, helping provide dedicated specialists and an elaborate branded demonstration space. Car-audio manufacturers are responding more modestly by financing their own displays as Best Buy retreats from providing them. In both cases, manufacturers that benefit from demonstrations are taking on more of their cost, better aligning the incentives of manufacturers and retailers to provide services that help sell the product.

Tuesday, September 22, 2026

When Winning Is a Budget Risk: Hedging Coaching Bonuses

Prediction-market trades have turned up whose payouts nearly match college football coaches' playoff bonuses. Five line up almost exactly with Lane Kiffin's bonuses at LSU. The schools didn't place them, but third parties acting for them plausibly did.

Why would a school bet on its own success? Coaching contracts promise big bonuses for making the playoffs, advancing and winning a title. A deep playoff run can leave the athletic department owing millions it didn't budget for. A contract that pays off when the team wins covers that bill when it comes due. Like a farmer locking in a crop price, the school gives up some upside in exchange for a predictable budget.

Why go through a third party? NCAA rules forbid athletic staff from betting on games, and prediction markets count. So a school can instead pay an insurer a premium, and the insurer buys the contracts itself.

Takeaways:

  • A performance bonus is a bill that only comes due when things go well.
  • If people are betting on whether that success happens, you can buy a bet that pays for the bill.
  • As budgets tighten and these betting markets grow, expect more of this.

Source: Josh Hendrickson, Insuring Against Success?, Economic Forces

Wednesday, September 16, 2026

Rewarding Judgement in AI Use


AI is changing which employee skills create value and how to incentivize these skills. EY recently announced a $100 million employee rewards program aimed at recognizing workers who develop “future-focused” capabilities and use technology to produce better outcomes. The interesting part is what EY has chosen to reward. Along with technology adoption, the firm emphasizes business acumen, judgment, adaptability, experimentation, collaboration, and innovation. As AI makes some technical capabilities more abundant, human judgment can become increasingly scarce and valuable. EY is not simply paying employees to use more AI; it is rewarding them for developing skills that make AI more productive.

That changes the incentive problem. If AI substitutes for routine research, analysis, or coding, producing more of those activities becomes a less useful measure of employee performance. Knowing which questions to ask, recognizing when an AI answer is wrong, exercising judgment when information is ambiguous, and finding new ways to combine AI with expertise can become more valuable. But these qualities are also difficult to measure. Counting hours, completed reports, or even AI usage is relatively easy; determining whether an employee exercised good judgment is not. EY's new program therefore allows employees at all levels to recognize colleagues, while other EY initiatives use simulations, coaching, and assessments of decision-making and collaboration to identify these less tangible skills.

Moving from objective output measures toward judgment, adaptability, and collaboration also changes the role of supervisors. Managers must have more discretion to decide whose contributions actually created value, making the quality and credibility of those evaluations more important. EY has argued that AI-era performance management should place greater weight on peer feedback, coaching, adaptability, and cross-functional impact, rather than relying simply on traditional manager ratings. It is also investing in more structured ways of assessing these skills: its new Career Residency program uses workplace simulations, coaching, and client situations to assess decision-making, collaboration, learning, and adaptation. As easily measured tasks become easier to automate, performance evaluation may consequently depend more on subjective judgment, but also on multiple evaluators and better ways of evaluating the evaluators.

Sunday, September 13, 2026

When driving is (almost) free


While I am pet-sitting for my sister in California, she is letting me use her beach-community house and electric car. It has been nice driving past gas stations with prices so high. She also has residential solar panels to charge her car (and run her other devices). The panels generate enough power that she is almost always "off the grid" with no electricity bill. So is the cost of driving zero? Should I be driving all over the place? 

Almost. The opportunity cost is what she would do with the surplus power she produces. Her utility will buyback her surplus power at $0.05-$0.08 per kwh while her retail rate is $0.45-$0.47 per kwh. Back in Texas these would be $0.07-$0.08 per kwh and $0.13-$0.19 per kwh. The opportunity cost in California is nearly 1/10 of the price while it is close to 1/2 in Texas. In Texas, I might drive a bit more if I had an EV and solar panels. In California, I would drive a lot more.

Wednesday, September 9, 2026

Save Early Kids

One of the most valuable decisions in retirement saving is when to start. Over the 50 years from 1976 through 2025, the S&P 500 delivered a compound annual return of about 11.82%, including reinvested dividends. Suppose a young worker had invested just $100 each month in an S&P 500 fund and earned that historical compound return until age 65. Starting at age 25 would produce about $922,000. Waiting until 30 reduces the ending balance to about $523,000, while waiting until 35 reduces it to about $295,000. Scraping together $100 when you are 25 is difficult, but if you can do it consistently, voila you will become a millionaire.

What makes the comparison striking is how little of the difference comes from the contributions themselves. Doubling your set-aside each month will merely double the ending balance. But by starting at 25 versus 30, you contribute only $6,000 more yet finish with roughly $399,000 more. Save 15% more and finish with 76% more. Compared with starting at 35, the early saver contributes just $12,000 more but finishes with about $627,000 more. The reason is compound growth: dollars contributed early earn returns, those returns earn returns, and the process repeats for decades. Of course, future stock returns may be lower than the past 50 years, and actual returns are anything but smooth. But the lesson does not depend on the return so much. The opportunity cost of waiting to save is not primarily the contributions you miss, it is the decades of compound returns those contributions could have earned.

You can use the SEC site to do your own “what if” scenarios.